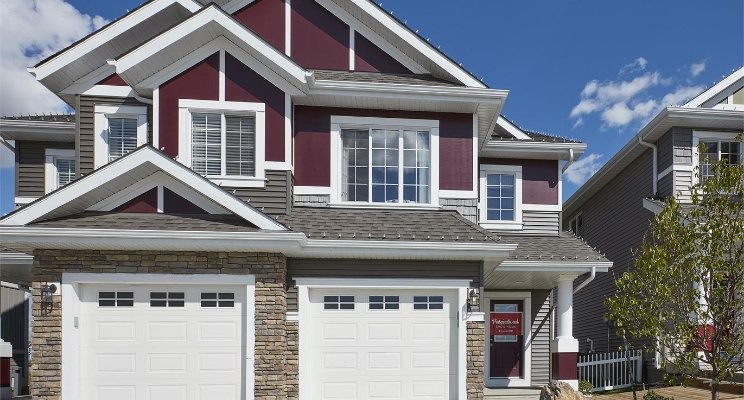
3 Must-Do’s When Selling Your House This YearIt’s exciting to put a house on the market and to think about making new memories in new spaces. However, despite the anticipation of what

Dated: December 11 2019
Views: 390
 ? Send me an email at zachary.hicks@exprealty.com
I've been a resident of the Greater Milwaukee Area my entire life. Real estate has given me the privilege of working with my neighbors and friends--aiding them in purchasing or selling their homes. Of....
3 Must-Do’s When Selling Your House This YearIt’s exciting to put a house on the market and to think about making new memories in new spaces. However, despite the anticipation of what
Is This the Year to Sell My House?If one of the questions you’re asking yourself is, “Should I sell my house this year?” consumer sentiment about selling today should
Your House May Be High on the Buyer Wish List This Holiday SeasonAround this time each year, many homeowners decide to wait until after the holidays to sell their houses. Similarly, others who
 Metro MLS - Milwaukee Data provided by Metro MLS. All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. IDX information is provided exclusively for consumers personal, non-commercial use and that it may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Information is supplied by seller and other third parties and has not been verified. Real estate listings held by brokerage firms other than eXp Realty in Milwaukee may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 - Multiple Listing Service, Inc. - All rights reserved.
Last Updated: September 24, 2026 12:20 PM UTC
 REALTORS® Association of Northeast Wisconsin All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s), nor eXp Realty in Milwaukee, nor RANWMLS shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than eXp Realty in Milwaukee may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 REALTORS Association of Northeast WI MLS, Inc. All rights reserved. Last Updated: September 24, 2026 12:24 PM UTC
